

Why a mobile-first credit path actually works for real people
I started thinking about credit differently after watching friends in Mexico City move from cash to smartphones during the 2020 pandemic surge—suddenly, the tools were everywhere and the gap to formal credit closed a bit. Mobile-first apps let you track a credit score, set reminders, and complete loan origination without a branch visit; that’s power in your pocket. If you need an immediate boost to show repayment history, consider simple options like didi prestamos to build a timely record while keeping control of interest rate exposure.
Concrete steps to create a flawless credit trail on your phone
Start with identity and small wins. Each step below is meant to be practical and measurable.
– Verify your identity inside the app and link a digital wallet or bank account so payments show up cleanly on statements.
– Begin with a small, manageable product (a credit-builder loan or micro-loan) and treat it like a scheduled habit. Loan origination can feel formal, but on mobile it’s just a workflow you repeat.
– Automate payments and keep utilization low. Low utilization and on-time payments move the needle on your credit score faster than opening lots of accounts.
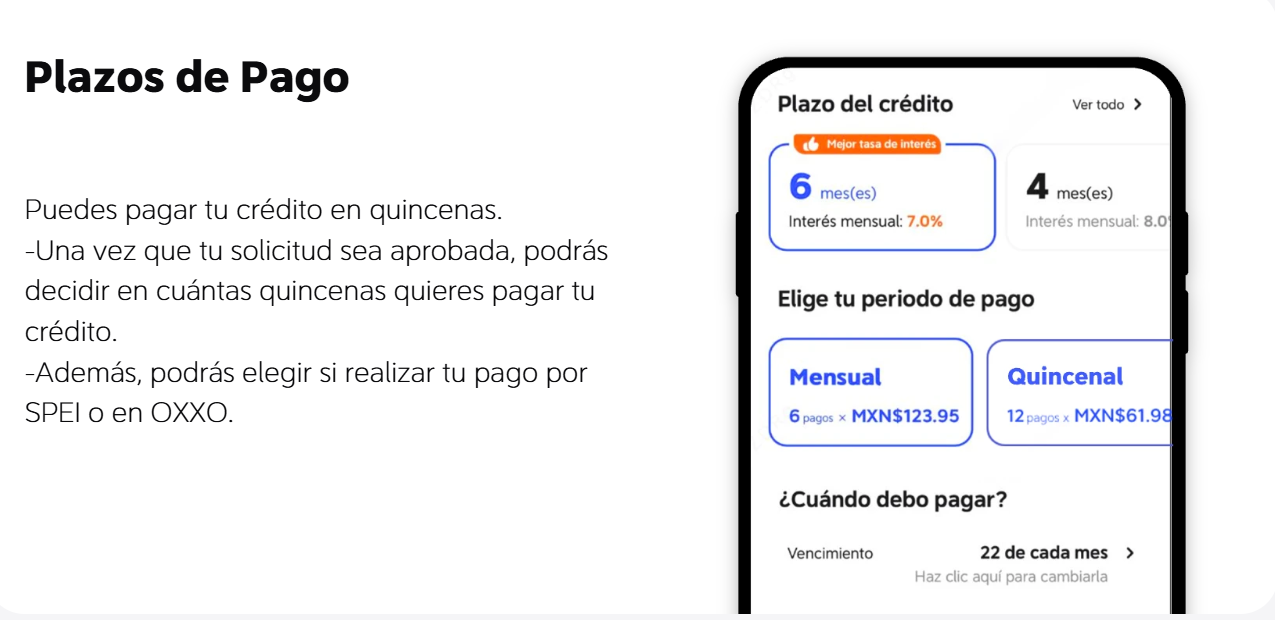
– Monitor APR and underwriting terms before you accept an offer—shorter terms with predictable fees beat variable surprises.
If you need instant liquidity for a planned repayment or emergency, some platforms provide prestamos en linea al instante that record activity promptly—use them intentionally, not habitually.
Common mistakes users make (and straightforward alternatives)
People often treat mobile lending like a convenience, not a record. That’s the mistake. Missing one payment creates a visible blemish; chasing the lowest nominal rate alone can hide high fees. Too many hard credit checks is another frequent misstep—each hard inquiry can slow progress.
Alternatives that still respect a mobile workflow: secured credit products, small recurring utilities on your account to show payment history, or a co-signed product. If a product’s underwriting feels opaque, step back. Choose transparency over a shiny fast approval. —I’ve seen founders sign up for every good-looking offer and end up hurting their score in six months.
Measure progress with three practical metrics
Track these consistently. They’re simple, objective, and map directly to better access later.
– On-time payment rate: aim for 98% or higher. This matters most.
– Utilization ratio across revolving lines: keep it under 30% of available credit.
– Account age and mix: steady, older accounts plus one small loan show maturity and responsible borrowing behavior.
Three golden rules when evaluating mobile credit tools
1) Transparency in costs: if the fees or APRs are hard to find, walk away. Clear pricing beats slick onboarding every time.
2) Data portability and statements: ensure you can export records or sync with your tax or budgeting tools—this makes proof of behavior straightforward.
3) Safety and identity verification: prefer platforms that use multi-factor checks and clear customer support channels; fraud hurts your history faster than late payments.
Measure, iterate, and treat your mobile lending history like product development—small releases, reliable updates, measurable outcomes. DiDi Finanzas fits naturally into that workflow for many users in Mexico because it combines straightforward products with clear repayment records—an actual bridge between a phone-based habit and a strong credit profile. —steady progress wins.